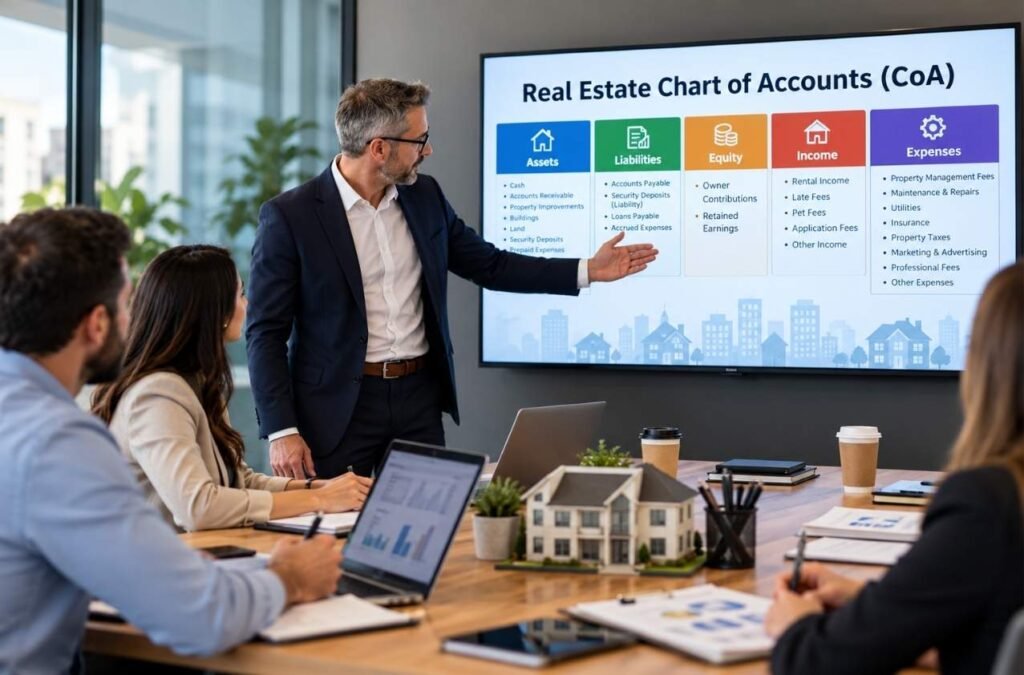
Good rental property bookkeeping depends on more than recording transactions as they happen. Everyone handling the books needs a clear way to decide where each entry belongs, how property details should be recorded, and which records support the figures.
A rental property Chart of Accounts (CoA) provides part of that foundation. Without a consistent structure, similar transactions may end up in different categories, making monthly reviews less reliable and corrections harder to trace.
This becomes more important when a property business grows, adds staff, or works with an outside bookkeeper. Clear account names and consistent tracking rules help people follow the same process instead of making separate choices for similar transactions.
This guide explains how to set up a CoA, establish a suitable account numbering system, and review the structure as your business changes. The focus is on creating a process you can use consistently, not just a list of accounts.
Key Takeaways
➤ A Chart of Accounts for real estate organizes rental income, expenses, assets, liabilities, and equity to support clear financial records and reports.
➤ Set up accounts based on your properties, ownership structure, and reporting needs. Use clear account names and numbering to keep records organized.
➤ Track multiple properties with property codes or classes, and maintain separate books when different legal entities require them.
➤ Classify transactions correctly. Refundable security deposits are liabilities, mortgage payments include principal and interest, and capital improvements may need depreciation.
➤ Review your CoA during month-end close, reconcile accounts, check supporting documents, and update categories when your rental business changes.
What Does a Real Estate Chart of Accounts (CoA) Do?
A Chart of Accounts (CoA) is the organized list of accounts used to record financial activity in your accounting system. Each account represents a type of transaction or balance. Together, these accounts form the structure behind your general ledger and financial reports.
For a rental property business, the CoA connects daily transactions with the financial information you need. When rent arrives, the income account records the revenue. When you pay an insurance bill, the relevant expense account records the cost. Asset and liability accounts track items such as property values and outstanding loans.
This structure supports three main reports:
1. Profit and loss statement: Shows income, expenses, and profit or loss over a period.
2. Balance sheet: Shows assets, liabilities, and equity at a specific date.
3. Cash flow statement: Shows how cash moves into and out of the business.
A CoA doesn’t replace your accounting records or supporting documents. It gives each transaction a consistent place in the system, making the resulting reports easier to review and understand.
Well-organized real estate bookkeeping categories also make it easier to trace entries when reviewing these reports. Professional real estate accounting services can help maintain this structure and keep financial reports clear, consistent, and useful for decision-making.
What Accounts Should a Rental Property Chart of Accounts (CoA) Include?
A rental property business needs accounts that reflect both its daily operations and its financial position. The right structure helps owners see where money comes from, what the business owes, and how property costs affect overall results. Reviewing real estate Chart of Accounts examples can help you identify suitable accounts for your business.
1. Assets
Assets are resources your business owns or controls. Common accounts include:
(i) Operating bank accounts
(ii) Rental property and land
(iii) Building and equipment
(iv) Prepaid expenses
(v) Accumulated depreciation
Keep property-related asset records clear enough to support future reporting and tax work.
2. Liabilities
Liabilities are amounts your business owes to others. Relevant accounts may include:
(i) Mortgage payable
(ii) Accounts payable
(iii) Accrued expenses
(iv) Refundable tenant security deposits
A refundable security deposit belongs in a liability account, as you may need to return it. Don’t treat it as rental income simply because the money entered your bank account.
3. Equity
Equity represents the owner’s interest in the business. Depending on the ownership structure, accounts may include owner contributions, owner distributions, and retained earnings.
Keep owner funding separate from rental revenue. This helps prevent money added by an owner from appearing as income earned through property operations.
4. Income
Income accounts record money earned through rental activity. Examples include:
(i) Rental income
(ii) Parking income
(iii) Laundry income
(iv) Late fees, where applicable
(v) Other property-related revenue
Create separate income accounts when the distinction helps you review performance. You don’t need a new account for every small revenue type if the extra detail doesn’t support a useful decision.
5. Expenses
Expense accounts record the costs of operating and managing properties. Common examples include repairs, maintenance, insurance, property taxes, utilities, management fees, mortgage interest, and depreciation expense.
Keep expense categories clear enough to support both management reports and tax review.
For U.S. rental property owners, the IRS Schedule E instructions provide a useful reference for classifying reportable rental income and expenses. Your bookkeeping accounts should also reflect your business activities and reporting needs. These rental property accounting categories should reflect the costs your business actually incurs.
How to Set Up a Real Estate Chart of Accounts (CoA)?
Setting up Chart of Accounts in accounting works best when you start with the information you need to manage your properties. A clear plan helps you choose useful categories, keep the structure consistent, and avoid rebuilding it as your portfolio grows.
This structure also supports multifamily and single-family accounting services and short-term rental accounting services, helping keep financial records organized across different property types.
1. Define your business and reporting needs
Start by listing the properties and rental activities covered by your books. Note whether you manage long-term rentals, short-term stays, multifamily buildings, or a mix of property types.
Next, decide what you need to review each month. You may want to compare property income, monitor repair costs, track outstanding loans, or prepare reports for owners. These needs will guide the accounts you create.
Also confirm which legal entities own the properties. One owner may hold several properties in one entity, while another may use separate entities. Your accounting setup should reflect the actual ownership and reporting structure.
2. Set up the main account categories
Create the five main account groups: assets, liabilities, equity, income, and expenses. Then add subaccounts where they provide useful detail.
For example, an owner may create separate expense accounts for insurance, repairs, property taxes, and utilities. This makes it easier to see what drives operating costs without reviewing every transaction individually.
Use the sample accounts from the previous section as a starting point. Remove categories that don’t apply, and add accounts for real activities that the standard list doesn’t cover.
3. Create a clear account numbering system
Account numbers help organize the ledger and make accounts easier to locate. Choose a consistent pattern and leave enough room to add accounts later.
An illustrative structure could use:
Number range | Account group |
1000–1999 | Assets |
2000–2999 | Liabilities |
3000–3999 | Equity |
4000–4999 | Income |
5000–5999 | Expenses |
These ranges are examples, not required accounting rules. Use a numbering system that fits your accounting setup, and avoid creating new number ranges without a clear reason.
Give accounts descriptive names, too. A label such as “Property Repairs” is more useful than a vague name such as “Other Costs.” Clear names make real estate accounting categories easier to identify when entering and reviewing transactions.
4. Align rental accounts with tax reporting needs
For U.S. residential rental owners, IRS Schedule E is a useful reference when organizing rental property income and expense categories. It helps connect bookkeeping records with the information reported on an individual tax return when Schedule E applies.
However, tax reporting and management reporting don’t always need identical levels of detail. You may need a separate account to review a cost across your properties, even when tax reporting groups that cost under a broader category.
Ask your tax professional to review unclear classifications. Don’t assume an expense is deductible simply because you’ve assigned it to an expense account.
5. Enter opening balances and test the setup
Before recording routine transactions, gather reliable records for bank balances, outstanding loans, property assets, and other relevant accounts. Enter opening balances based on supported records rather than estimates.
Then record a few sample transactions and review the reports they produce. Check whether rental income appears under the right heading, loan balances make sense, and expenses are easy to identify.
Resolve unexplained differences before using the setup for regular bookkeeping. A short review at this stage can prevent errors from carrying into later reports.
※ If you’re looking beyond account setup, read our real estate accounting guide to learn more about managing rental property finances.
How to Track Multiple Properties in a Chart of Accounts (CoA) Without Mixing Their Finances?
A single account structure can support several properties, but the bookkeeping must still show where each transaction belongs. The right tracking method helps owners compare results, review property costs, and prepare useful reports across their portfolio.
1. Use property-level tracking for income and expenses
Suppose you own three rental homes. Each home has rent income, insurance costs, repairs, and utility bills. You could create separate expense accounts for every home, but that may make your account list harder to manage.
Instead, consider using property codes, classes, or tracking fields within your accounting system. You can record each transaction under the relevant expense account and link it to the property involved.
For example, all three homes could use one Repairs and Maintenance account. A property identifier would show which home received each repair service. You could then review the total repair costs across the portfolio or examine one property’s expenses.
Choose a method that supports the reports you need and works with your accounting system. Apply it consistently so the reports remain useful over time.
2. Know when separate books may be needed
Property tracking and separate accounting records serve different purposes. A tracking field may work when several properties belong to one legal entity and share one set of books.
Separate legal entities may need separate books, depending on their ownership, legal duties, and reporting needs. Don’t assume that adding a property code is enough to separate the finances of distinct entities.
Review your ownership structure with your accountant before choosing the setup. This decision affects how you record transactions, manage balances, and prepare financial reports. Property management accounting services can support this process by helping property owners organize records according to their reporting and bookkeeping needs.
How to Classify Common Rental Property Transactions Correctly?
Choosing an account name is only part of accurate bookkeeping. Rental transactions can involve different financial treatments even when money enters or leaves the same bank account, so owners need a consistent way to classify each entry.
Transaction | Accounting treatment |
Refundable security deposit | Record as a liability when received, if you may need to return it. |
Advance rent | For U.S. tax purposes, generally report it as rental income when received. |
Mortgage payment | Split principal repayment from interest expense. |
Routine repair | Record as an expense when the applicable accounting rules support that treatment. |
Capital improvement | Record as an asset when capitalization rules apply, then account for depreciation as required. |
Owner contribution | Record as equity rather than rental income. |
These distinctions matter because the bank statement alone doesn’t tell you how to classify a transaction.
For example, a mortgage payment may reduce your bank balance, but the full payment isn’t necessarily an expense. The principal portion reduces the loan balance, while the interest portion may be an expense. Your lender’s statement can help you identify each part.
The IRS distinguishes refundable security deposits from advance rent. A refundable deposit generally isn’t rental income when received. However, if the landlord retains part or all of the deposit, the tax treatment depends on why it’s retained. A deposit designated as the tenant’s final rent payment counts as advance rent and is generally taxable when received.
Repairs and improvements also need careful review. A repair may qualify as a current expense, while an improvement may need to be capitalized and recovered through depreciation. Ask a tax professional when the distinction isn’t clear.
How to Review and Maintain Your Chart of Accounts for Real Estate?
A Chart of Accounts for rental property needs regular review as properties, transactions, and reporting needs change. A simple review process helps keep the structure clear, supports reliable financial statements, and reduces the risk of errors building up over time.
1. Review the accounts during month-end close
Use month-end close to check whether your records reflect the month’s activity. Reconcile bank and credit card accounts, investigate unusual balances, and review transactions that remain uncategorized.
Then compare property-level income and expenses with the reports you expect to see. Check key balances against supporting records, including lender statements and invoices. If a number looks wrong, trace it to the original transaction instead of changing an account balance without evidence.
Keep receipts, bills, loan statements, and other documents that support the entries. These records help explain what happened if you need to review a transaction later or prepare your tax return.
2. Update the structure when the business changes
Your CoA should change when your reporting needs change, not whenever a new transaction appears. Before adding an account, ask whether the new category will help you make a decision or meet a reporting need.
Remove duplicate accounts from active use when appropriate, but check existing balances and records before making changes. Keep account names clear, and document major changes so your accountant can follow the history.
Review the setup after buying a property, changing ownership structures, or adding a new rental activity. If the reports no longer answer your business questions, the structure may need a careful update.
※ If you manage multiple rental properties, use this real estate month-end close checklist to review property income and expenses, reconcile accounts, and catch bookkeeping errors before they affect your reports.
Build a Clearer Chart of Accounts for Real Estate With VRSapients!
A Chart of Accounts for rental property should reflect how your rental business operates and what you need to learn from your financial reports. Clear categories help you review income, understand costs, track obligations, and keep records ready for tax work.
Start by checking whether your accounts match your properties, ownership structure, and reporting needs. Remove needless complexity, but keep enough detail to explain transactions and compare property results. Review the setup during month-end close, and update it when your business changes.
VRSapients offers real estate bookkeeping, Chart of Accounts (CoA) setup, account reconciliation, and property-level financial reporting. Our team helps property owners and managers organize their records, track transactions, and maintain clear financial reports as their portfolios grow.
Write to us here, schedule an appointment, or call (+1) 315-961-2217 to review your property accounts and improve your financial reporting.
Frequently Asked Questions
What is a real estate Chart of Accounts (CoA)?
What is a real estate Chart of Accounts (CoA)?
A real estate Chart of Accounts (CoA) is a list of accounts you use to organize your property’s financial transactions. It groups rental income, expenses, assets, loans, and owner contributions into clear categories. This helps you understand property performance, review costs, and prepare accurate financial reports.
How should a Chart of Accounts (CoA) be structured?
How should a Chart of Accounts (CoA) be structured?
You should structure your Chart of Accounts (CoA) around five main groups: assets, liabilities, equity, income, and expenses. Give each account a clear name and, if useful, a number. Add subaccounts only when they help you track costs or prepare reports. Keep the structure consistent as your rental business grows.
What accounts should a real estate business have?
What accounts should a real estate business have?
Your real estate business may need accounts for bank balances, rental properties, mortgages, owner contributions, rental income, repairs, insurance, property taxes, utilities, and mortgage interest. You may also need accounts for tenant security deposits and depreciation. Choose accounts based on your properties, ownership structure, and reporting needs.
How to organize income and expenses for rental properties?
How to organize income and expenses for rental properties?
To organize income and expenses for rental properties, create separate accounts for rental income and key costs, such as repairs, insurance, property taxes, and utilities. If you own several properties, use property codes or tracking fields to show where each transaction belongs. This lets you compare property costs without creating a separate account for every property.
Does a security deposit count as rental income?
Does a security deposit count as rental income?
No, a security deposit doesn’t count as rental income if you plan to return the deposit to your tenant. In the U.S., you generally record a refundable security deposit as a liability, not rental income. If you keep it under the lease terms, its tax treatment may change. A deposit used as final rent counts as advance rent.